Is Geopolitics Opening New Doors for EV Localization Worldwide?
By Hanjie Wang
While trade tensions continue to dominate international headlines, the rapid growth of electric vehicle (EV) industry has attracted less attention. Yet this transformation is already having a ripple effect in emerging markets and developing economies (EMDEs).
As governments race to decarbonize economies, the EV sector has become one of the most competitive arenas of global industrial activity. Policy tools like tariffs and subsidies have returned to the forefront of economic policymaking, often framed in the language of climate action, supply chain security and job creation. Against this backdrop, how are evolving geopolitical dynamics reshaping the global EV world at a more fundamental level?
A new working paper from the Boston University Global Development Policy Center explains the trend. Drawing on global trade policy data and expert interviews, it shows that developing countries are now the leading adopters of localization policies in the EV sector. Importantly, the study reflects a powerful interaction between long-standing domestic development drives and a changing geopolitical environment that has expanded the policy space for industrial intervention.
What Are EV Localization Policies, and Why Do They Matter?
Localization policies are public policy measures that require or incentivize firms to produce, source or invest locally as a condition for market access or public support. In the EV sector, these policies often take the form of local content requirements, domestic production mandates tied to procurement or incentives or rules that favor locally assembled vehicles and components.
Unlike tariffs, which directly raise the cost of imports and indirectly incentivize the purchase of domestic production, localization policies directly shape how and where production takes place. They are therefore especially attractive to governments seeking to build domestic manufacturing capacity, create jobs, attract foreign direct investment (FDI) and move up global value chains. Historically, such policies have been widely used in the automotive industry, particularly by developing countries seeking to nurture infant industries. The trend was prevalent in the late 1990s and early 2000s where developing countries such as the Philippines, China, Brazil, Indonesia, India and Russia all implemented localization policies to foster domestic automobile industry. Even so, localization has long been controversial. Past experience, taking the case of internal combustion engine industries for instance, suggests that these policies often generate mixed economic outcomes and expose countries to legal challenges under World Trade Organization (WTO) rules. This has imposed significant constraints on developing countries seeking to build their automotive industries, often slowing or pausing efforts to expand domestic car production.
More recently, we observe clustering and peaks in the adoption of localization policies between 2019 and 2024, driven primarily by three developing countries: Russia, India, and Indonesia. This raises a puzzle: why are developing countries, embracing localization policies again, notably in the EV sector?
Mapping The Global Rise of EV Localization
Using data from the Global Trade Alert, the study tracks all EV-targeting trade interventions between 2008 and 2024 and identifies nearly 100 measures that explicitly involve localization. The results reveal two striking patterns.
First, EV-related trade intervention has been on the rise since 2008 (see Figure 1) and is now widespread across both advanced economies and EMDEs. Financial grants, tariffs and state-backed financing dominate the policy toolkit in countries such as China, the United States and Russia. This reflects the broader global revival of industrial policy under the “green” or climate-related banners.
Figure 1: EV-targeting Trade Interventions, 2008–2024

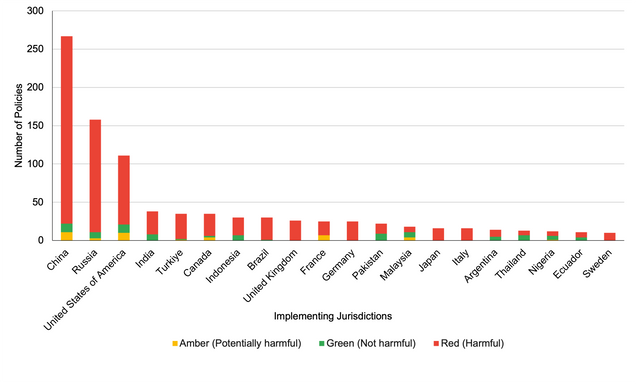
Second, and more unexpectedly, localization policies are geographically concentrated in EMDEs. As Figure 2 shows, countries such as Russia, India, Indonesia, Türkiye, Brazil and several African and South Asian economies have adopted more EV-specific localization measures than most advanced economies. By contrast, the US and France are the only two advanced economies that appear among the top adopters, and even there, localization plays a smaller role relative to subsidies and public finance.
Figure 2: Counts of EV-Targeting Trade Measures Across the Top 20 Countries, 2008–2024
This pattern marks a clear departure from the conventional narrative, which often emphasizes advanced economies as the main drivers of industrial policy resurgence. In the EV sector, developing countries are not simply reacting to global trends—they are actively shaping them.
Domestic Development Goals Still Matter—But They Are Not Enough
Developing countries have strong incentives to use localization to promote industrial development, protect employment and attract investment. EVs offer a rare opportunity to enter a fast-growing, technologically dynamic industry rather than remain locked into low-value-added activities such as raw material extraction.
Interviews with industry experts and policy observers confirm that these domestic motivations are central. Governments see localization as a way to anchor EV assembly, batteries or upstream processing at home; firms see it as a condition they must meet to access new markets. Countries with large domestic markets, existing automotive industries, competitive labor costs or critical mineral endowments—such as nickel, lithium, or cobalt—are especially well positioned to deploy these policies effectively.
But these factors alone cannot explain the timing and scale of recent adoption. Many of these domestic conditions have existed for decades. What has changed is the international political economy environment in which localization policies are now being pursued.
How Geopolitics Has Expanded Policy Space
The paper argues that geopolitical change has created an enabling context for localization policies, reducing the external risks that once constrained them. This shift operates through three interrelated channels.
First, great power preferences have changed. The US and the European Union, two long-standing champions of free trade, have themselves embraced selective industrial policy in response to competition with China. Measures such as the US Inflation Reduction Act, EU industrial strategies and new trade defense actions against Chinese EVs signal a retreat from strict free-trade orthodoxy. When advanced economies openly use localization-linked incentives at home, it becomes harder to delegitimize similar policies elsewhere.
Second, international norms have shifted. Analysis of United Nations General Assembly speeches shows a growing tendency for governments to frame industrial policy (including localization), in terms of economic security, employment and technological sovereignty. What was once portrayed as protectionist or deviant behavior is increasingly justified as sensible statecraft in an era of geopolitical tension and supply chain vulnerability.
Third, the enforcement capacity of international institutions, especially that of the WTO, has weakened. Since 2019, the paralysis of the Appellate Body has reduced the credibility of dispute settlement. While legal risks have not disappeared, the likelihood of swift and decisive punishment for localization policies has declined. For many governments, this lowers the perceived cost of experimentation.
Together, these changes have widened the policy space available to developing countries. Localization policies that might once have been politically or legally risky now appear more legitimate, feasible and defensible.
Why We Highlight Chinese EVs in This Story
Geopolitics also shapes firm behavior which in turn reinforces localization policy adoption efforts. As access to US and EU markets becomes increasingly constrained for China-made EVs, Chinese firms starts deepening their search for alternative markets. Developing countries now emerge as key destinations, not only for exports but also for overseas production and investment. This dynamic strengthens host countries’ bargaining power. Facing intense competition at home, Chinese EV firms are often willing to accept localization requirements in exchange for market access. For example, in early 2026, BYD announced that it is rapidly localizing its production and supply chain at its Camacari factory in Bahia, Brazil, aiming to source 50 percent of vehicle components locally by January 2027. For governments in EMDEs, this creates a rare opportunity to leverage foreign investment for domestic industrial goals.
China’s own position is revealing. Despite having made broad and sustained use of domestic industrial policies in the EV sector overall —backed up by strong state involvement—China has adopted few EV-specific localization measures at home. This approach reflects its role as a global supply-side leader with a more outward-oriented industrial strategy, placing less emphasis on shielding the domestic market.
Implications for Development and Global Governance
The rise of EV localization has important implications for developing countries, Chinese EV firms and the rest of the world.
- For developing countries, localization can be a powerful industrial policy tool—but only if it is embedded in a credible, coordinated strategy. Policies that focus narrowly on assembly risk creating low-value enclaves. Those that reward technological learning, supplier development and skills upgrading are more likely to yield durable benefits.
- For firms, especially Chinese EV manufacturers, localization is becoming an unavoidable feature of global expansion. Navigating diverse national requirements will be central to long-term competitiveness.
- At the international level, the spread of localization policies challenges the free-trade paradigm. As industrial policy becomes normalized across development levels, global governance frameworks will need to adapt balancing developmental aspirations with the risks of fragmentation and inefficiency.
Ultimately, the study suggests that geopolitics does not replace domestic political economy as a driver of industrial policy. Instead, it acts as a catalyst, amplifying existing domestic development ambitions. Whether this expanded policy space endures remains uncertain. For now, it is reshaping how and where the global EV industry is built.
*
Read the Working Paper