Green Growth or Commodity Dependence? The LAC-China Relationship in 2025

By Rebecca Ray
In 2024, Latin America and the Caribbean (LAC) had a record trade deficit with China, amounting to 1.4 percent of regional GDP. At the same time, the region’s exports to China re showing signs of shifting down the value chain, as the top five LAC-China exports are now raw materials with no value-added. Nonetheless, the relationship is likely to continue growing as the world undergoes an energy transition: green energy and green transportation are becoming top drivers of Chinese investment in LAC. These are among the findings of the 2025 edition of the China-LAC Economic Bulletin.
Trade: Increasingly Imbalanced
As Figure 1 shows, China’s 2024 exports to LAC rebounded, recovering almost all the ground that they lost in a slow 2023. However, LAC’s exports to China continued the previous year’s decline, resulting in a record regional trade deficit with China.
Figure 1: China-LAC Exports, LAC-China Exports and Balance, 2004-202

One reason behind this volatility in the China-LAC trade relationship is the increasing role of raw materials in LAC exports to China, with only the most minimal local transformation. Figure 2 shows the region’s top five exports to China over the last decade. Unrefined copper ores and concentrates are now the dominant product in the trading relationship, accounting for nearly one-fourth of all LAC revenue from trade with China. In contrast, refined copper products such as wires and sheets have now fallen out of the top five products, replaced with frozen beef.
Figure 2: Top LAC-China Exports, 2015-2024

As a result of these trends, LAC trade balances with China vary dramatically across the region, with mineral exporters such as Peru and Chile showing strong trade surpluses and more diversified economies such as Mexico showing significant trade deficits.
Figure 3: National LAC-China Trade Balances, 2024, % of GDP

Infrastructure: Transportation Surge
Just as LAC’s purchases of China’s exports have risen recently, so have LAC’s purchases of China’s infrastructure services. Figure 4 shows trends over the last 20 years in Chinese infrastructure contracts in the LAC region. These contracts include projects with designated clients—usually national or sub-national governments—and Chinese construction service providers, who do not take equity stakes in the final projects. These contracts have doubled in total scale over the last decade, particularly in the transportation sector.
Figure 4: Chinese Infrastructure Contracts in LAC

The most recent infrastructure projects have been concentrated among higher-income LAC countries such as Panama and Chile, both of which contracted with China Railway Tunnel Group to build underground sections of public transit systems. Notwithstanding the dominant role of these new transportation projects, power transmission continues to be another important sector. Power transmission was particularly important in Chile and Brazil, whose tremendous renewable energy generation potential is concentrated in locations that are distant from the main consumer bases. To maximize the benefit of those resources, both countries opted to contract with Chinese firms to deploy high voltage lines that can transmit the resulting energy over long distances with minimal losses.
Across the transportation and energy sectors, green energy and transportation are taking a dominant role. LAC countries are increasingly turning to Chinese firms as partners in pursuing their public transit, rail and renewable energy goals.
China’s Outbound Foreign Direct Investment in LAC: Green Power, Transit Accelerate
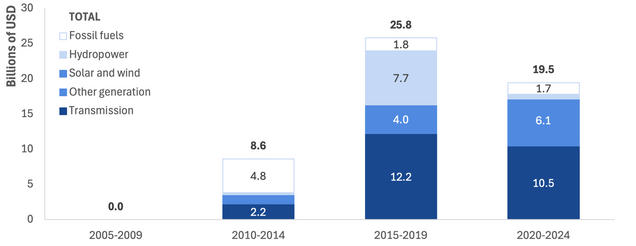
Green energy and transport are taking a central role in Chinese firms’ outbound foreign direct investment (OFDI) in LAC. Over the last five years, these trends are visible within the top three OFDI sectors: mining, minerals and metals; energy generation and transmission; and automotive manufacturing. These three sectors accounted for 86 percent of all China-LAC OFDI over the last five years. Figure 5 shows the trends within each of these sectors:
Figure 5: China-LAC OFDI in Top Sectors, by Environmentally Relevant Sub-Sectors
A. Mining, Minerals and Metals

B. Energy Generation and Transmission
C. Automotive Manufacturing

As Figure 5A shows, within the mining sector, the overwhelming majority of China-LAC OFDI is now concentrated in energy transmission minerals such as lithium and copper, while OFDI in fossil fuels has taken a much smaller role. In energy, Figure 5B illustrates that solar and wind have drawn the largest share of energy generation, while energy transmission continues to play an important role (as the China-LAC infrastructure trends show, new investments in energy transmission are often necessary to connect geographically remote solar and wind producing regions to national grids). Finally, according to Figure 5C on automotive manufacturing, new Chinese OFDI activity is concentrated in electric vehicles and in factories that produce both electric and internal combustion vehicles. This trend is new, as electric and hybrid vehicles were nearly completely absent from China-LAC OFDI before 2020.
Development Finance: Bolstering National Development Finance Institutions
China’s overseas development finance (ODF)—sovereign lending by China’s two development finance institutions (DFIs), the China Development Bank and Export-Import Bank of China —rebounded slightly in 2024 to $2.8 billion, still well below pre-2020 levels. Figure 6 compares this lending to that of the World Bank and the Inter-American Development Bank. While China was a predominant source of development finance during the previous decade, in recent years it has played a less central role the region’s sovereign finance needs.
Figure 6: LAC Development Finance from Top Sources, 2008-2024

Furthermore, over the last few years, Chinese ODF has been almost exclusively channeled through national DFIs such as Brazil’s Banco do Brasil and Banco Nacional de Desenvolvimento Econômico e Social (BNDES). Figure 7 shows the sectoral composition of Chinese, World Bank and IDB development finance in the last five years: almost all of China’s lending has been in the finance and financial intermediaries sector, while World Bank and IDB lending has been concentrated in public administration and social protection.
Figure 7: LAC Development Finance by Source and Sector, 2020-2024

Through its reduced scale in lending and the increasing importance of bolstering national DFIs, Chinese DFIs have backed away from direct project selection, planning and oversight. Instead, they have opted to collaborate more indirectly, providing resources for national institutions that have more experience in those tasks in the LAC context.
Future Prospects
The direction of the China-LAC relationship over the next few years are likely to be significantly influenced by shifting trade tensions among China, LAC and the United States. For example, tariffs between China and the United States have significantly increased Chinese demand for soybeans and beef from Brazil and Argentina. Reflecting concern for the environmental impact of expanding soy and beef production on the Brazilian Amazon and Cerrado ecosystems, Brazil and China have begun developing a voluntary certification scheme (“soja china”) aimed at developing traceability and accountability for land use changes associated with this new production.
At the same time, Mexico and Brazil have both raised the possibility of new trade barriers with China. Mexico has proposed establishing a 50 percent tariff on products from any country with which it does not already have a free-trade agreement (FTA). This move will impact trade with China much more than any other partner, as China accounts for over 80 percent of Mexico’s non-FTA imports. Brazil has opened an anti-dumping investigation into Chinese, Indian and Indonesian steel. In practice, almost all Brazilian steel imports are Chinese, so this move will primarily affect imports from China.
These tensions are likely to be exacerbated by falling global commodity prices. As Figure 8 shows, of the four top LAC-China export commodities, only copper is expected to remain at or above its current prices over the next few years.
Figure 7: Major China-LAC Export Commodity Prices, Actual and Projected

Given the importance of the China-LAC relationship for growing sectors such as green energy and transit, it is likely that the relationship will continue taking on more importance for both parthers. Thus, it is important for LAC governments to maximize the benefits for their own development goals and similarly minimize the macroeconomic, environmental and social risks stemming from the centrality of agricultural and mineral commodity production. Efforts such as the “soja china” certification program and the attraction of Chinese electric vehicle factories can be important elements of such a strategy moving forward.
Read the 2025 China-LAC Bulletin